Many people in the US and Europe dream of having a dog: long walks, cozy evenings on the sofa, road trips, funny photos. But behind the cute moments is a serious question: “How much does a dog really cost every year?”
The honest answer is: it depends. A small, healthy mixed-breed dog in a quiet town will cost much less than a large purebred dog with health issues in a big city. Still, we can break down the main expenses and give realistic ranges so you can plan ahead instead of guessing.
In this guide, we’ll cover:
The difference between first-year costs and typical yearly costs
Average yearly expenses for small, medium and large dogs
Where your money actually goes: food, vet care, insurance, grooming, training and more
How city vs rural life, and US vs Europe, can change the numbers
Tips to control costs without sacrificing your dog’s wellbeing
1. First-Year Costs vs Typical Yearly Costs
One of the biggest mistakes new dog owners make is focusing only on the first month (bed, bowls, leash) and forgetting about the first year, which is usually the most expensive.
1.1 Why the first year is more expensive
In the first year, you pay for things you won’t repeat every year, such as:
Adoption fee or breeder price
Initial vaccinations and boosters
Spay/neuter surgery (if not already done)
Microchipping and registration
Basic equipment: bed, crate, collar, harness, leash, toys, bowls
Basic training classes (especially for puppies)
On top of that, puppies need:
More frequent vet visits
Higher-calorie food
Extra supplies for house training (cleaners, pads, etc.)
1.2 Typical pattern over a dog’s life
First year: Most expensive due to setup and surgery.
Adult years (2–7 or so): More stable costs: food, basic vet care, insurance, grooming, occasional training.
Senior years: Costs often rise again due to chronic illnesses, medications and more frequent vet visits.
When planning, don’t just ask “Can I afford the adoption fee?” — ask “Can I afford this dog for the next 10–15 years?”
2. Rough Yearly Cost Ranges by Dog Size
Every dog is different, but size is a simple way to get rough yearly ranges. Below are very general ranges for a “typical” year (after the first year), assuming:
Decent quality food
Routine vet care and parasite prevention
Some grooming and training costs
No major emergencies
2.1 Small dogs (up to ~10 kg / 22 lb)
Typical yearly cost range might include:
Lower end: A healthy, mixed-breed small dog in a low-cost area, simple lifestyle.
Higher end: A purebred small dog in a city, with insurance, premium food and grooming.
2.2 Medium dogs (~10–25 kg / 22–55 lb)
Medium dogs eat more and may need more robust equipment. Expect yearly spending to rise compared with small dogs, especially on food and medications (which are often dosed by weight).
2.3 Large and giant dogs (>25 kg / 55 lb)
Large dogs are usually the most expensive to keep:
They eat significantly more food.
Medications, flea/tick products and anesthesia doses are higher.
Some large breeds are prone to joint problems that require long-term treatment.
Travel, boarding and housing restrictions may add extra cost.
While exact currency numbers vary by country and city, the pattern is clear: larger dog = larger yearly budget, sometimes dramatically so.
3. Where Your Money Actually Goes (Category Breakdown)
To plan your own budget, it’s more useful to think in categories than in one big number. Let’s go through the main categories and how they change with dog size and lifestyle.
3.1 Food and treats
For many owners, food is the single biggest continuous cost.
Small dogs: Often relatively inexpensive to feed, even on good-quality food.
Medium dogs: Moderate food cost; quality choices matter more than ultra-high-end brands.
Large dogs: Food can become a major monthly expense, especially if you choose premium brands or special diets.
Add a bit for treats, chews and training rewards. These can quietly become a large part of your budget if you don’t monitor them.
3.2 Routine vet care
Most healthy adult dogs need:
One or two wellness exams per year
Vaccine boosters as recommended
Year-round or seasonal flea, tick and worm prevention
Dental checks and occasional cleanings
In both the US and Europe, vet services in major cities are usually more expensive than in rural areas. Large dogs cost more for parasite control and medications because doses are based on weight.
3.3 Pet insurance
If you choose dog insurance, it often becomes one of your bigger yearly expenses – but in exchange, it can protect you from sudden, huge bills.
Small mixed-breed dogs: Often have lower premiums.
Large or purebred dogs: Higher risk = higher premiums.
Your yearly insurance cost will depend on your chosen deductible, reimbursement rate and coverage limits. You can also skip insurance and build an emergency savings fund instead (or combine both).
3.4 Grooming and coat care
Grooming costs depend more on coat type than size:
Short-haired breeds: Basic home brushing and occasional baths – low grooming costs.
Long-haired or curly-coated breeds: Professional grooms every few weeks or months – can be a major yearly expense.
Nails, ears and basic hygiene need attention for all dogs. If you can learn some grooming tasks at home, you can significantly reduce costs over time.
3.5 Training and behavior
Training is a “hidden” cost that saves you money later. Even a well-behaved dog benefits from:
Puppy classes or basic obedience courses
Occasional refresh sessions for recall or leash walking
Behavior support if problems like anxiety or reactivity appear
Group classes are usually cheaper than one-on-one sessions. Spending a bit on training can prevent far more expensive problems such as destroyed furniture, neighbor complaints or even legal issues.
3.6 Boarding, pet sitting and dog walking
Your own lifestyle has a huge influence here.
If you travel often, boarding or pet sitting for a dog adds up quickly.
If you work long hours away from home, regular dog walking or daycare may be necessary.
Working from home and having friends or family nearby can reduce these costs dramatically.
3.7 Licenses, microchips and miscellaneous admin
Many cities and regions require:
Dog licenses or registrations
Microchipping (often a one-time cost)
These amounts are usually small compared with food or vet bills but should still be included in your yearly budget.
3.8 Replacing gear and household wear-and-tear
Over time, you will probably buy:
New beds when old ones flatten or tear
Replacement collars, harnesses and leashes
Additional toys, puzzle feeders and chews
You might also need to repair or replace household items damaged by a young or bored dog: rugs, shoes, remote controls, furniture. Good training reduces these “surprise” costs.
4. How Location and Lifestyle Change the Numbers
Two owners with the same breed can have very different yearly costs depending on where and how they live.
4.1 City vs rural
City life: Higher vet and grooming prices, more expensive boarding and daycare, higher pet deposits and “pet rent” in apartments, but easier access to services.
Rural or small-town life: Lower service prices on average, but longer travel distances to vets or specialists and possibly higher fuel costs.
4.2 US vs Europe
Broadly speaking:
In both regions, large cities tend to be more expensive than smaller towns.
Different countries have different typical vet fee levels, insurance markets and housing rules.
Health insurance for dogs is more widely used and varied in some countries than others.
Instead of fixating on exact currency amounts, it’s better to think in terms of percentage of your monthly income that you’re comfortable spending on a dog.
4.3 Your personal lifestyle choices
You can “dial up” or “dial down” your dog budget with daily choices:
Premium organic raw diet vs solid mid-range kibble
Weekly professional grooming vs home brushing and occasional trims
Frequent daycare and dog sports vs more DIY walks and home training
None of these are automatically right or wrong. The key is to know what you are choosing and make sure your overall budget can handle it.
5. Don’t Forget Senior Years and Medical Surprises
Dogs rarely stay in the “cheap adult phase” forever. As they age, new costs appear.
5.1 Chronic medications
Senior dogs often need:
Pain relief and anti-inflammatory drugs for arthritis
Heart medications
Thyroid or hormone treatments
Special diets for kidney, liver or digestive issues
Each medication may be affordable by itself, but together they can noticeably increase your monthly spending.
5.2 More frequent vet visits and tests
Twice-yearly or quarterly check-ups
Regular blood and urine tests
More imaging (X-rays, ultrasound) for new problems
These visits are important to maintain quality of life, but you should expect your annual vet bill to grow as your dog ages.
5.3 Emergencies and surgery
No budget guide is complete without acknowledging emergencies. Even with good prevention, dogs sometimes:
Swallow foreign objects
Get into fights or accidents
Develop sudden illnesses that require hospitalization or surgery
A single emergency can equal or exceed your “normal” yearly costs. That’s why pet insurance or a strong emergency fund is so important.
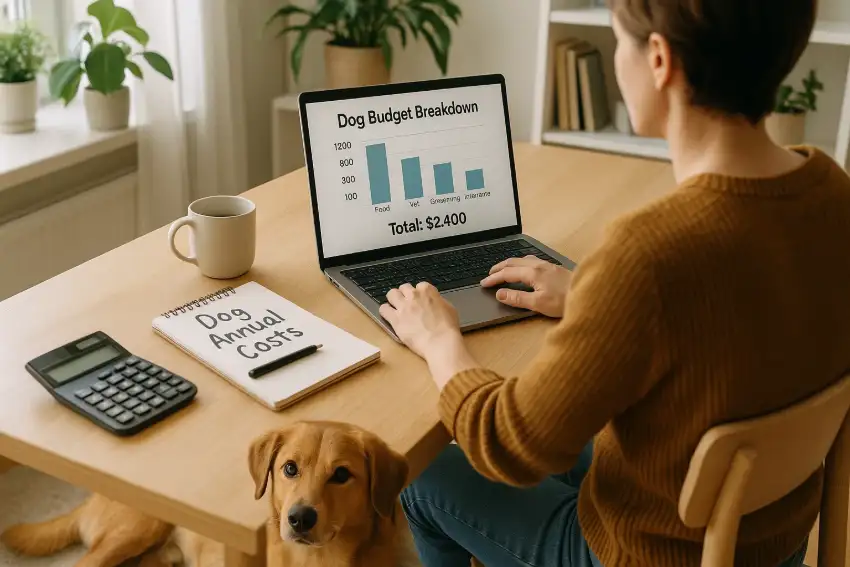
6. How to Build Your Own Yearly Dog Budget
Instead of searching for one magic number, use these steps to build a budget tailored to your dog and your life.
6.1 Step 1: Estimate monthly basics
Add up:
Food and treats (realistic estimate, not wishful thinking)
Insurance premium (if applicable)
Routine preventives (flea/tick/worm products)
Average monthly share of yearly vaccines and check-ups
Multiply by 12 to get a baseline yearly cost.
6.2 Step 2: Add irregular but predictable expenses
Grooming (total yearly trims and baths divided into a yearly amount)
Training classes or behavior consults
Boarding, pet sitting or dog walking based on your travel and work patterns
Licensing fees and microchip updates
Replacement of beds, collars, toys and gear
6.3 Step 3: Plan for surprises
Decide how you will handle:
Emergency vet bills and surgery
Senior-year medications and tests
Big lifestyle changes (moving, new baby, job change) that affect pet care costs
You might:
Set aside a fixed amount each month into a “dog emergency fund”.
Choose an insurance policy that fits your risk level and budget.
Do both, if you want a stronger safety net.
6.4 Step 4: Check if the number feels comfortable
Look at your final estimated yearly cost and ask:
Is this realistically affordable without stress?
What would happen if my income temporarily dropped?
Am I willing to adjust my own spending in other areas to support this dog?
If the answer feels tight, consider:
Choosing a smaller or lower-maintenance breed
Delaying adoption until your finances are more stable
Adjusting some “nice-to-have” items (e.g., fewer paid services, more DIY care)
7. Final Thoughts: A Dog Is a Long-Term Financial Commitment
Over a full lifetime, most dogs cost many thousands in food, vet care, insurance, grooming, training, travel and little “extras”. That can sound scary – but it is also the price of more than a decade of companionship, routine, exercise and emotional support.
A dog is not just a one-time purchase; it is a long-term financial and emotional commitment. The “right” yearly cost is the one where:
Your dog receives appropriate medical care, nutrition and enrichment.
You are not constantly anxious or resentful about money.
You can say “yes” to necessary treatment without destroying your own stability.
If you take the time to understand the categories, estimate your own numbers and build a realistic plan, you won’t just be “hoping it works out”. You’ll be choosing dog ownership with open eyes – and that gives both you and your future dog a much better chance of a happy, secure life together.