Vet bills in the US and Europe keep going up. A simple emergency can cost hundreds or even thousands of dollars or pounds – which is why more dog and cat owners are looking at pet insurance.
But when you start comparing policies, you quickly see two big categories:
Accident-only pet insurance
Comprehensive (accident + illness) pet insurance
On the surface, accident-only is cheaper and looks attractive. But is it enough for real life? This guide breaks down how each type of plan works, what they actually cover, and how to choose the right level of protection for your pet and your budget.
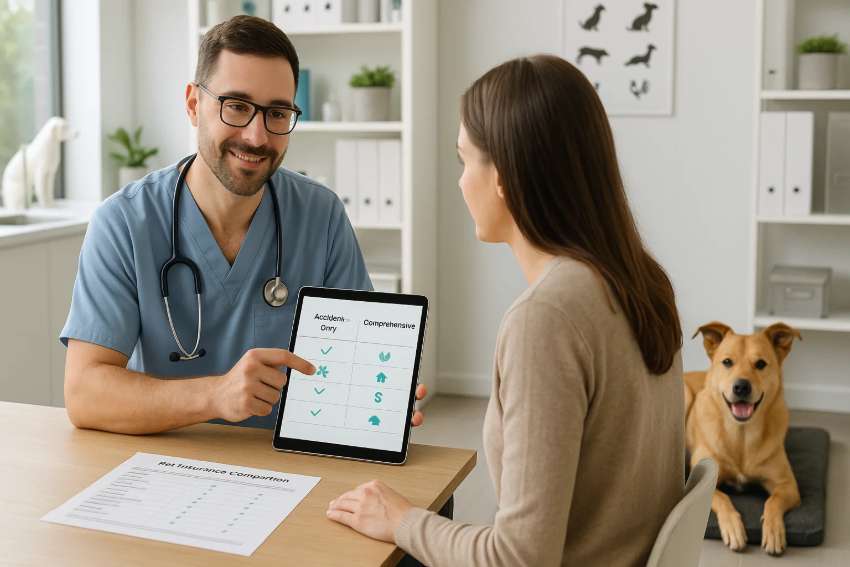
1. Key Differences at a Glance
| Feature | Accident-Only Plan | Comprehensive Plan (Accident + Illness) |
|---|---|---|
| What it covers | Sudden accidental injuries only (car accidents, falls, cuts, broken bones, etc.) | Accidents and most illnesses (infections, cancer, diabetes, arthritis, etc.) |
| Routine care | Usually not covered | Usually not covered unless you add a wellness add-on |
| Monthly price | Lower | Higher |
| Protection against big bills | Only if they come from accidents | Accidents + major illnesses (often the most expensive part of vet care) |
| Best for | Very tight budgets, older pets with pre-existing illnesses, or as a basic safety net | Most puppies, kittens and healthy adult pets; owners who want real peace of mind |
2. What Accident-Only Pet Insurance Really Covers
Accident-only plans are the “bare minimum” type of pet insurance. They usually help with vet bills when something sudden and external happens to your pet – not internal illnesses.
2.1 Typical accidents covered
Being hit by a car or bike
Falling from a height (stairs, balcony, window)
Deep cuts and wounds from fights or sharp objects
Bone fractures and dislocations
Foreign body ingestion (for example, swallowing a toy or sock) – sometimes classed as accident, depending on the insurer
Burns, some poisonings, electric shock
2.2 What accident-only does not cover
Accident-only plans usually do not pay for:
Cancer treatments
Diabetes, kidney disease, heart disease
Ear infections, chronic skin allergies
Arthritis, hip dysplasia, cruciate ligament disease
Viral or bacterial illnesses (parvo, pneumonia, etc.)
If your dog needs chemotherapy or your cat develops kidney disease, accident-only insurance won’t help – you’ll pay those bills yourself.
2.3 Pros of accident-only plans
Cheaper monthly premium than comprehensive cover.
Offers a basic safety net for sudden injuries.
Can be an option if your budget is extremely tight but you still want some protection.
2.4 Cons of accident-only plans
No illness cover – many of the most expensive vet bills are illness-related.
Can create a false sense of security if you think “my pet is insured” but most scenarios aren’t covered.
You might still face difficult decisions if your pet develops a chronic disease you can’t afford to treat long term.
3. What Comprehensive Pet Insurance Covers
Comprehensive plans are sometimes called:
“Accident & illness” policies
“Full cover” or “complete” plans (names vary by company)
They are designed to cover most of the health problems pets are likely to face over their lifetime – not just accidents.
3.1 Typical coverage areas
A good comprehensive plan usually covers:
Accidents (same as accident-only)
Short-term illnesses:
Vomiting and diarrhoea
Infections (ear, eye, skin, urinary tract)
Respiratory illnesses
Chronic and long-term diseases:
Allergies and ongoing skin issues
Arthritis and joint problems
Kidney, liver or heart disease
Endocrine diseases (diabetes, thyroid issues, Cushing’s, etc.)
Cancer diagnosis and treatment
Some dental problems caused by accident or illness (details vary)
3.2 What comprehensive plans usually don’t include by default
Routine vaccinations and annual check-ups
Neutering/spaying
Flea, tick and worm treatments
Food, toys and everyday supplies
Some insurers offer wellness or preventative care add-ons for an extra fee that help cover routine costs – but these are optional and vary a lot between providers.
3.3 Pros of comprehensive plans
Real financial protection for both accidents and most illnesses.
Helps pay for expensive surgeries, hospital stays and medications.
Gives you more freedom to say “yes” to the best treatment instead of worrying only about money.
3.4 Cons of comprehensive plans
Higher monthly premium than accident-only.
Pre-existing conditions are usually not covered (especially in older pets).
You still need to read the fine print – coverage limits, exclusions and waiting periods matter a lot.
4. Types of Comprehensive Policies: Lifetime vs Time-Limited
Within “comprehensive” insurance, there are sub-types that make a big difference to long-term value:
4.1 Lifetime (or “reinstatement”) coverage
Each year you renew, your pet is covered for ongoing conditions up to a set annual limit.
Example: Your dog develops diabetes at age 4 – a lifetime policy can keep covering diabetes treatment year after year, as long as you renew and stay within annual limits.
4.2 Annual or time-limited coverage
Illnesses are covered for a set period (for example, 12 months from first symptoms) or up to a fixed total amount for that condition.
After this time or limit is reached, that condition may no longer be covered.
When comparing comprehensive plans, check:
Is this lifetime cover or just time-limited?
What is the annual or per-condition limit the insurer will pay?
Two comprehensive plans can look similar in price, but one may give much better protection over your pet’s whole life.
5. Cost Comparison: Accident-Only vs Comprehensive (Example)
Prices vary by country, insurer, breed, age and location, but here’s a simple example to illustrate the difference in risk, not exact numbers:
Scenario A: Accident-only plan
Monthly premium: lower
Your dog swallows a toy and needs emergency surgery:
If the insurer classifies this as an “accident”, they may cover most of it.
Two years later, your dog develops cancer:
Cancer treatment costs thousands – you pay 100% of this, as it’s an illness.
Scenario B: Comprehensive plan
Monthly premium: higher
Emergency surgery for swallowed toy:
Covered, minus your deductible and copay.
Cancer diagnosis and treatment:
Also covered up to your plan’s annual or lifetime limits.
Over a healthy pet’s lifetime, you might pay more in premiums with a comprehensive plan. But if your pet ever faces a serious illness, the comprehensive plan can easily save you thousands and protect you from making heartbreaking choices based purely on money.
6. When Accident-Only Insurance Might Make Sense
Accident-only insurance is not worthless. It can be a practical compromise in some situations:
Very tight budgets: You genuinely cannot afford comprehensive cover, but want some protection for major injuries.
Older pets with known illnesses: Those illnesses may be excluded anyway; accident-only can still help with sudden injuries.
Short-term “bridge” coverage: For example, while you’re between jobs or moving and can’t yet commit to a more expensive plan.
Just be honest with yourself: if your pet develops a serious illness, accident-only won’t help. You’ll need your own savings, credit or alternative plans for those scenarios.
7. When Comprehensive Insurance Is Usually the Better Choice
For most dog and cat owners in the US and Europe, comprehensive insurance is the option that actually protects your wallet.
It’s especially worth considering if:
You have a puppy or kitten with many years ahead.
Your pet’s breed is known for:
Joint problems (hips, elbows, knees)
Allergies or skin disease
Heart conditions, kidney disease or cancer
You would struggle to pay for a multi-thousand-dollar emergency or long-term treatment out of pocket.
In these cases, paying more each month for a comprehensive, preferably lifetime, plan is often smarter than gambling that your pet will “only ever have accidents”.
8. How to Decide: Questions to Ask Before You Buy
Before choosing accident-only or comprehensive pet insurance, ask yourself:
What am I really insuring against?
Just car accidents and injuries?
Or also cancers, chronic diseases and age-related problems?
How much could I pay myself if my pet got sick?
If you can comfortably cover several thousand in cash, maybe you can accept more risk.
If not, a stronger policy is often safer.
What is my pet’s age and breed risk?
Flat-faced breeds, large dogs and some purebreds have higher medical risk.
Younger pets are usually cheaper to insure and easier to get comprehensive cover for.
Do I understand the exclusions?
Pre-existing conditions
Waiting periods
Specific breed or hereditary exclusions
Take time to compare at least a few insurers, read sample policies, and use online quote tools before deciding. You don’t have to pick the first “cheap” option you see.
9. Summary: Accident-Only vs Comprehensive in One Sentence
If you want a simple rule of thumb:
Accident-only = budget safety net for injuries only. Comprehensive = real protection for the health problems most pets actually face.
For most US and European pet owners, a good comprehensive, lifetime-style plan chosen early in your pet’s life offers the best mix of financial protection and peace of mind. Accident-only plans can still be useful in some situations – but make sure you understand exactly what is not covered before you rely on them.