Food, litter, vaccines, toys, grooming, vet bills… Pet expenses in the US and Europe often arrive in small pieces, spread across different days and shops. It’s easy to feel like money just “disappears” without knowing where it went.
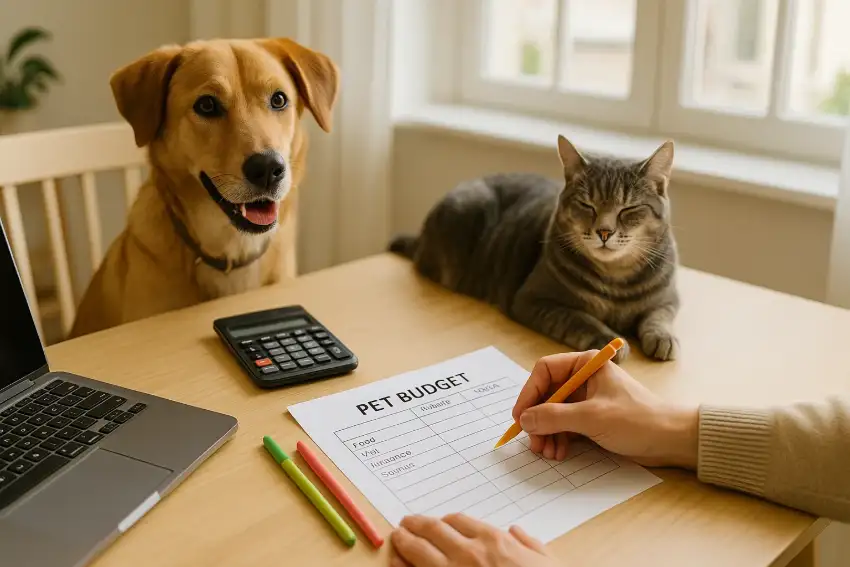
A simple monthly pet budget gives you control. It doesn’t have to be complicated or perfect. The goal is to:
See clearly what you already spend on your dog or cat
Plan ahead for annual costs like vaccines and check-ups
Decide how much you want to save for emergencies
Find gentle ways to save money without hurting your pet’s wellbeing
In this guide, we’ll walk through a step-by-step system you can use whether you have one cat in a small apartment or several dogs in a suburban house.
1. Understand the Three Types of Pet Costs
Before you build a budget, it helps to sort expenses into three simple groups:
1.1 Fixed monthly costs
These are regular, predictable expenses that happen every month or almost every month, for example:
Food
Litter (for cats)
Pet insurance premiums
Medications your pet takes every day (for chronic conditions)
Dog walker or daycare (if used regularly)
1.2 Variable but expected costs
These don’t happen every month but are easy to predict across a year, such as:
Annual vaccines and wellness exams
Flea, tick and worm prevention (often bought every 1–3 months)
Grooming appointments or nail trims
New toys, beds, collars, scratching posts
Boarding or pet sitting during holidays
You can smooth these costs by turning them into a small monthly “envelope” in your budget.
1.3 True surprises and emergencies
These are the scary ones:
Emergency vet visits
Surgery after an accident
Sudden illnesses that need tests and hospitalization
You handle these with a pet emergency fund and/or pet insurance, not with your normal monthly budget alone.
2. Step One: Track What You Already Spend
Before you decide what your pet budget “should” be, find out what it actually is right now.
2.1 Look back over the last 2–3 months
Check your bank and card statements.
Search for pet store names, vet clinic names and online pet orders.
Include supermarket purchases where you bought pet food or litter.
2.2 Write everything down in simple categories
Use a notebook, spreadsheet or budgeting app. For each month, create lines like:
Food and treats
Litter (if you have cats)
Routine vet (check-ups, vaccines, parasite prevention)
Grooming
Insurance
Toys, beds and accessories
Boarding/pet sitting/dog walking
Other (anything that doesn’t fit above)
2.3 Average your spending
If one month had a big vet visit and another month was quiet, take the average of 2–3 months. This gives a more realistic picture of your “normal” spending.
3. Step Two: Turn Yearly Costs Into Monthly Amounts
Many pet expenses are annual or occasional, but your budget works better if you “pretend” they are monthly.
3.1 List all yearly or irregular costs
Vaccines and annual wellness visit
Blood tests (if your vet recommends them yearly)
Flea, tick and worm treatments for the year
Dental cleanings (for some pets, every 1–2 years)
Average yearly grooming total (for breeds that need clipping)
Typical yearly holiday pet care (boarding, sitters)
3.2 Convert each to a monthly equivalent
For each item:
Estimate the total cost per year.
Divide by 12 to get a monthly amount.
For example:
If yearly vaccinations and check-ups cost you a certain amount, divide by 12 and add that to your monthly budget.
If you usually spend a certain amount on boarding each year, divide by 12 and set that aside monthly.
3.3 Create a “pet sinking fund”
Transfer this total monthly amount into a savings sub-account or budgeting “envelope”. When yearly bills arrive, you already have money waiting.
4. Step Three: Decide on an Emergency Protection Strategy
Your monthly pet budget also needs to consider rare but expensive events. Choose one of three basic strategies:
4.1 Insurance-focused strategy
Accident-and-illness insurance is your main protection against large bills.
Your monthly budget includes the insurance premium plus a small amount for deductibles and uncovered items.
Ideal if you struggle to save large amounts quickly or own a high-risk pet.
4.2 Savings-focused strategy
You build a dedicated pet emergency fund without using insurance.
Your monthly budget includes a fixed amount that goes into this fund.
Best for owners who have strong saving habits and accept more risk.
4.3 Hybrid strategy
You carry insurance with a reasonable deductible for major problems.
You also save a smaller monthly amount for deductibles, exclusions and routine surprises.
Many families find this balance gives both flexibility and peace of mind.
5. Step Four: Build Your Monthly Pet Budget Template
Now you’re ready to create a simple template you can reuse every month.
5.1 Core categories to include
Your template might look like this:
Food and treats – regular monthly cost
Litter (cats) – regular monthly cost
Insurance premium – fixed monthly amount (if you have it)
Routine care fund – monthly share of yearly vaccines, tests, parasite prevention, grooming, toys, boarding
Emergency fund contribution – amount you save every month toward your pet emergency fund
Services – regular dog walking, daycare or training (if used)
5.2 Optional sub-categories
If you like more detail, you can split:
Routine care fund → “Vet care”, “Grooming”, “Toys & enrichment”, “Travel/boarding”
Services → “Dog walker”, “Daycare”, “Training classes”
5.3 Keep the template somewhere visible
Pin it on your fridge.
Save it as a note in your phone.
Create a simple spreadsheet with one tab per month.
6. Step Five: Test Your Budget Against Reality
A budget is only useful if it survives contact with real life. For the next 1–3 months:
6.1 Track spending and compare to your plan
Write down each pet expense as it happens (or once a week from your bank app).
At the end of the month, compare actual spending to your budget for each category.
6.2 Adjust instead of blaming yourself
If you spend more than expected, ask:
Was this a one-time spike, or a pattern?
Did I underestimate the real cost of food, litter or vet care?
Do I need to cut somewhere else, or simply accept a slightly higher budget?
The goal is not “perfect budgeting”. The goal is accurate budgeting.
7. Step Six: Find Safe Places to Save Money
Once you have a clear picture of your monthly pet costs, you can look for smart savings that don’t hurt your dog or cat.
7.1 Safer places to cut
Unnecessary luxury items: multiple fancy beds, designer outfits, premium-only brands that don’t add real health benefits.
Excessive treats: use smaller training treats and fewer high-calorie snacks.
Duplicate toys and accessories: rotate toys instead of constantly buying new ones.
7.2 Places you should NOT cut
Core nutrition (don’t switch to very poor-quality food just to save a little).
Essential vet care like vaccines, parasite control and important medications.
Pain relief or necessary treatment for real medical problems.
7.3 Talk to your vet about budget-friendly choices
Ask whether there are safe generic medications instead of brand names.
Ask if there are practical, lower-cost diagnostic plans when money is tight.
Ask which changes would save money without harming your pet’s health.
8. Multi-Pet Households: One Budget, Many Animals
If you have several pets, it can be helpful to create:
One combined “household pet budget” for shared items (toys, beds, litter bought in bulk)
Separate lines for costs that belong to each animal (food type, insurance policy, chronic medications)
This shows you:
Which pet costs the most (and why)
Where bulk buying really saves money
How much extra a new pet would truly add to your monthly budget
9. Review and Refresh Your Pet Budget Once a Year
Your pet budget is not a one-time project. Things change:
Food prices and vet fees go up over time.
Your dog or cat moves from adult to senior and needs more medical care.
Your own income or lifestyle may change.
9.1 Schedule a yearly check-up—for your budget
Once a year (for example, after your pet’s annual vet visit), review your budget categories.
Update amounts based on the latest bills and quotes.
Adjust your emergency fund target if your pet’s health or age has changed.
9.2 Celebrate what’s working
Notice:
Which habits helped you avoid panic when bills arrived.
How much you’ve built in your emergency fund.
Any financial stress that has become easier since you started budgeting.
10. Final Thoughts: A Budget Is a Tool, Not a Punishment
A monthly pet budget is not about turning your life with your dog or cat into a spreadsheet. It’s about:
Reducing surprise and anxiety
Making sure you can afford basic care and emergencies
Protecting your own financial stability
Giving you permission to enjoy your pet without constant money guilt
When you know what you spend and why, you can say “yes” to the important things with confidence—food, comfort, essential medical care—and say “no” to the extras that don’t truly matter.
That’s what a good pet budget really does: it turns random stress into calm, informed choices, so you and your pet can focus on what matters most—living a happy, secure life together.