One big emergency vet visit can feel like a small financial earthquake. A broken leg, sudden surgery or overnight hospitalization in the US or Europe can cost as much as a holiday, a new laptop or even a month of rent. That’s why so many dog and cat owners ask the same question:
“Is pet insurance actually worth it, or should I just save money myself?”
There is no single answer that fits everyone. But you can make a confident decision if you understand:
What pet insurance really covers (and what it doesn’t)
When insurance usually makes sense – and when it might not
How to combine insurance with savings for better protection
What to look for when comparing policies
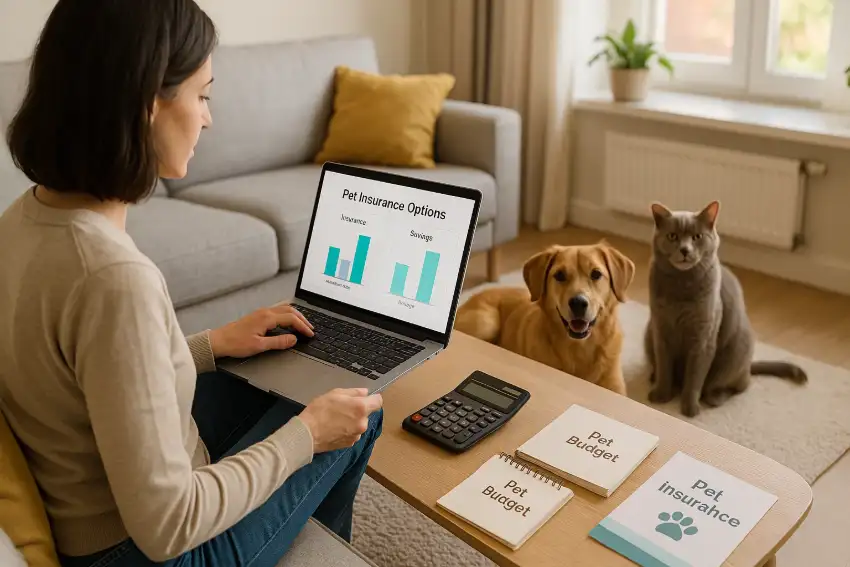
1. What Pet Insurance Actually Is (In Simple Terms)
Pet insurance is a way to protect yourself from large, unexpected vet bills by paying a smaller, predictable amount each month or year.
1.1 Key words you’ll see in policies
Premium: The amount you pay each month or year to keep the policy active.
Deductible (or excess): The part of the bill you must pay yourself before the insurance starts to reimburse you.
Co-pay / reimbursement rate: The percentage the insurance pays after the deductible (for example, they pay 80%, you pay 20%).
Annual or per-condition limit: The maximum amount the insurance will pay each year or for a specific illness/injury.
Exclusions: Things the policy does not cover (for example, pre-existing conditions, certain breed conditions, routine check-ups).
Pre-existing condition: Any illness or injury your pet had before the policy started or during the waiting period – usually not covered.
Waiting period: A short time after you buy the policy when some or all claims are not yet covered.
Think of pet insurance as a shock absorber: it doesn’t remove all costs, but it can stop a single emergency from destroying your budget.
2. Types of Pet Insurance Coverage
Most policies fall into a few basic categories:
2.1 Accident-only
Covers injuries from accidents: car hits, falls, bites, broken bones.
Usually cheaper but does not cover illnesses like cancer, kidney disease or infections.
Can be a minimal safety net if your budget is very tight.
2.2 Accident and illness
Covers accidents and most illnesses (subject to exclusions).
Usually the main type of policy owners consider.
Helps with big bills for chronic diseases, surgeries and long-term treatment.
2.3 Add-ons and wellness plans
Some companies offer extra coverage for routine care: vaccines, flea/tick prevention, wellness exams, dental cleanings.
These are more like prepaid plans than true insurance.
Sometimes useful for budgeting, but they don’t protect against very large, rare bills in the same way as accident/illness coverage.
3. When Pet Insurance Often Is Worth It
Insurance is not magic, but in some situations it tends to be a good deal or at least a strong form of protection.
3.1 You have limited savings
If a four-figure vet bill would be very difficult or impossible to pay, insurance becomes more attractive.
The premium is like paying a small “membership fee” for the ability to say “yes” in an emergency.
3.2 Your pet is young and healthy
Policies started when pets are young usually:
Have fewer exclusions and
Offer better coverage before any conditions become “pre-existing”.
Starting early means your pet is protected during the riskiest times: accidents, genetic diseases appearing, unexpected illnesses.
3.3 Your pet is a high-risk breed or large dog
Large and giant breed dogs often face joint issues, ligament ruptures and higher surgery costs.
Certain breeds are prone to heart disease, breathing issues, skin problems or cancers.
For these dogs, a single surgery can cost as much as several years of premiums.
3.4 You want emotional peace of mind
Some owners simply don’t want to face “Can I afford this treatment?” in a crisis.
Knowing that a big part of the bill will be reimbursed can reduce guilt and stress when making medical decisions.
4. When Pet Insurance Might Not Be the Best Choice
Insurance is not automatically right for everyone. In some situations, another strategy may make more sense.
4.1 Very tight budgets where premiums hurt essentials
If paying the premium means struggling with rent, food or basic needs, insurance might increase stress instead of reducing it.
In that case, focusing on a small emergency fund and low-cost preventive care may be more realistic.
4.2 Very old pets with many pre-existing conditions
If your pet is already senior and has several diagnosed health issues, new policies may:
Exclude those conditions completely, or
Offer limited coverage at high premiums.
In that case, careful savings and clear communication with your vet might be more useful than starting insurance late.
4.3 Owners with strong savings and high risk tolerance
If you already have a large, dedicated emergency fund and are comfortable with risk, you may prefer to “self-insure” by saving.
This works best if you consistently put aside money and won’t be tempted to spend it.
5. Savings vs Insurance: How to Think About the Trade-Off
A simple way to think about it:
Insurance: You pay a predictable fee now to protect yourself from a possible large bill later.
Savings only: You keep your money, but if a big emergency happens soon, your savings might not be ready.
5.1 Time is the key factor
If your pet gets seriously ill or injured early in life, insurance usually “wins” financially.
If your pet stays very healthy for many years, you might pay more in premiums than you ever claim back – but you had peace of mind during that time.
5.2 Mixed strategy: often the most realistic
Many owners use both:
Insurance for rare, very expensive events, and
Savings for deductibles, co-pays and smaller issues.
This strategy reduces the risk of both “I can’t afford surgery” and “I have zero savings”.
6. How to Decide If Pet Insurance Is Worth It for You
Here’s a practical decision process you can walk through.
6.1 Step 1: Look honestly at your finances
Could you pay for a major emergency (for example, surgery and a few days of hospitalization) without going into serious debt?
Do you currently have a dedicated pet emergency fund?
How stable is your income?
6.2 Step 2: Consider your pet’s risk profile
Species and size (large dogs vs small dogs vs cats)
Breed-related issues (talk to your vet about typical health risks)
Lifestyle: indoor vs outdoor, city vs countryside, very active vs quiet
6.3 Step 3: Get a few real quotes
Collect quotes from several companies for your pet’s age, breed and location.
Compare:
Monthly premium
Deductible amount
Reimbursement rate (for example 70%, 80%, 90%)
Annual limits and lifetime limits
Exclusions and waiting periods
6.4 Step 4: Compare to at least one “big bill” scenario
Ask your vet what a typical emergency might cost in your area (for example, foreign object surgery or treatment for a broken leg). Then:
Roughly estimate how much you would pay with and without insurance.
Remember to include premiums + deductible + co-pay in the insured scenario.
This won’t give a perfect answer, but it helps you see if insurance is mainly buying you protection and peace of mind or also likely to save money in a realistic situation.
7. How to Choose a Pet Insurance Policy (If You Decide to Buy)
If you decide insurance is worth it, the next question is: which policy?
7.1 Coverage questions to ask
Does it cover both accidents and illnesses, or accidents only?
Are hereditary and congenital conditions covered?
Is dental treatment covered, and under what conditions?
Does it cover long-term chronic illnesses for the lifetime of your pet, or only for a limited time/amount?
7.2 Money questions to ask
What is the deductible? Is it per year or per condition?
What percentage of each bill do they reimburse after the deductible?
What is the annual limit and the lifetime limit?
How do premiums change as your pet ages?
7.3 Practical questions to ask
Can you use any licensed vet, or do you have to stay in a specific network?
Do you pay the vet and then claim reimbursement, or can they work directly with the insurer?
How easy is the claims process (app, online form, paper)?
Are there good reviews from other pet owners in your country?
A slightly more expensive policy with clear coverage and easy claims can be better value than the absolute cheapest policy with many hidden exclusions.
8. Common Mistakes and Myths About Pet Insurance
8.1 “If I get insurance, I don’t need savings.”
You will still need money for:
Deductibles and co-pays
Exclusions and routine care
Small issues that you choose not to claim
A small emergency fund + insurance is stronger than insurance alone.
8.2 “Insurance covers everything now that I have a policy.”
Policies always have exclusions and limits.
Anything that started before the policy or during the waiting period is usually not covered.
Reading the fine print is boring but essential.
8.3 “I’ll wait until my pet gets older or sick, then I’ll buy insurance.”
Once a problem is diagnosed, it is normally considered “pre-existing” and excluded.
The best time to start coverage is usually when your pet is still young and healthy.
8.4 “If I don’t get back more than I pay in premiums, insurance was a waste.”
Insurance is not a savings account; it’s a safety net.
You don’t say car insurance was a “waste” if you never have a bad crash – it protected you from the risk.
Pet insurance works the same way.
9. Example Scenarios: Who Might Choose What?
Here are simplified examples to show how different owners might decide.
9.1 Owner A: Young indoor cat, limited savings
Lives in a city, small apartment.
Steady but modest income, little emergency savings.
Wants to avoid choosing between debt and treatment if something serious happens.
Likely choice: Accident & illness insurance with a moderate deductible, plus slowly building a small emergency fund.
9.2 Owner B: Large, active dog, outdoor adventures
Hikes, runs and travels with their dog often.
Knows large dogs face higher orthopedic risks and more expensive surgeries.
Can afford premiums but not a sudden very large bill.
Likely choice: Comprehensive accident & illness insurance with a solid annual limit, plus some savings for deductibles and travel-related risks.
9.3 Owner C: Older small dog, strong savings
Dog is already senior with a few chronic conditions.
Owner has a good job and substantial emergency savings.
New policies are expensive and exclude existing issues.
Likely choice: No new insurance; focus on savings, preventive care and clear communication with the vet about realistic treatment plans.
10. Final Thoughts: Worth It or Not?
Pet insurance is not about “winning” money from the company. It’s about:
Protecting yourself from large, unexpected vet bills
Giving your dog or cat access to treatment options you might otherwise struggle to afford
Reducing the emotional shock of emergencies
For many owners in the US and Europe – especially those with limited savings, large dogs or high-risk breeds – pet insurance is worth serious consideration. For others with strong savings and lower-risk pets, careful self-insurance may also be a valid choice.
The best decision is the one that fits your real finances, your pet’s health and your own feelings about risk. If you take the time to understand your options now, you’ll be better prepared when life throws you and your pet a surprise later – and that preparation is often worth more than any single bill.