Getting a dog in the US or Europe isn’t just an emotional decision – it’s also a long-term financial commitment. Food, vaccines, grooming, training, vet bills, pet sitting… over 10–15 years, the real cost of a dog can be much higher than the adoption or breeder fee.
There is no single “correct” number because expenses depend on size, breed, lifestyle and your own choices. But you can understand the main cost categories and build a realistic yearly budget.
In this guide, we’ll walk through:
The difference between small, medium and large dogs in yearly cost
Core yearly expenses: food, vet care, parasite prevention and insurance
Optional but common costs: grooming, training, walking and boarding
How lifestyle (city vs rural, active vs relaxed) changes the numbers
How to build your own yearly dog budget step by step
1. Why Dog Yearly Costs Vary So Much
Before talking about categories, it helps to understand what actually changes the total from one dog to another.
1.1 Size: the biggest driver
Small dogs eat less food, need lower doses of medication and are cheaper to groom and board.
Medium dogs sit in the middle for most categories.
Large and giant dogs are often dramatically more expensive – especially for food, joint medications and surgeries (which use more anesthesia and pain relief).
1.2 Breed and health risks
Some breeds have higher risk of joint issues, skin problems, breathing difficulties or heart disease.
These dogs may need more vet visits, more imaging, more medication and sometimes expensive surgery.
Insurance premiums are often higher for high-risk breeds.
1.3 Lifestyle and location
City vs rural: city vet clinics, groomers and pet sitters often charge more.
Activity level: active dogs that hike, run or do sports may need more gear and may have more minor injuries.
Owner lifestyle: long working hours can mean dog walkers and daycare; frequent travel means boarding or pet sitters.
With these factors in mind, let’s break down the yearly cost by category so you can build a picture for your own dog.
2. Yearly Cost Category 1: Food and Treats
Food is one of the largest ongoing dog expenses – and one of the easiest to underestimate.
2.1 What affects yearly food cost
Size and energy level: big, active dogs eat a lot more than small, low-energy dogs.
Food quality: very cheap foods may lead to health problems; very premium boutique diets may be more marketing than real benefit.
Wet vs dry: wet food is usually more expensive per calorie; many owners use a mix.
2.2 How to keep food costs under control (without harming health)
Choose a reputable, nutritionally complete food in a sensible price range.
Feed measured portions based on your vet’s advice and your dog’s body condition.
Use small treats for training – you don’t need huge, expensive biscuits to reward good behavior.
Limit table scraps and high-calorie snacks that add cost and risk obesity.
For most households, food + treats will be a predictable, budgetable monthly cost once you find the right diet and portion size.
3. Yearly Cost Category 2: Routine Vet Care and Parasite Prevention
Even healthy dogs in the US and Europe need regular veterinary care every year. Skipping this usually costs more later.
3.1 Routine vet care
Typical planned yearly expenses include:
Annual or semi-annual wellness exam
Core vaccine boosters (frequency depends on your vet’s schedule and local rules)
Optional vaccines based on risk (for example, kennel cough or tick-borne diseases in some areas)
Dental checks and occasional professional cleanings
Seniors and dogs with chronic conditions may also need:
Regular blood and urine tests
Blood pressure checks or heart scans
More frequent exams and medication adjustments
3.2 Parasite prevention
Most dogs need year-round or seasonal protection against:
Fleas and ticks
Intestinal worms
Heartworm in some regions
The cost depends on your dog’s weight, the products you use and how often you treat – but this is an important part of your yearly budget. Untreated parasites can cause anemia, skin infections, organ damage and serious disease.
4. Yearly Cost Category 3: Pet Insurance or Emergency Savings
The biggest financial shocks for dog owners come from emergencies and serious illnesses: surgery, hospitalization, intensive care, complex diagnostics.
4.1 Pet insurance
If you choose insurance, your yearly cost includes:
Monthly or yearly premiums
Deductibles and co-pays when you make claims
Premiums are usually higher for:
Large or giant breeds
Breeds with known health issues
Older dogs starting a policy later in life
Insurance doesn’t make vet care “cheap”, but it spreads the risk of big bills across many owners. It turns rare, huge expenses into predictable monthly costs.
4.2 Emergency savings fund
If you don’t use insurance – or even if you do – you should consider a separate savings pot for:
Accidents and sudden illnesses
Unexpected surgeries
Large diagnostic workups (X-rays, ultrasound, CT/MRI)
A strong dog budget includes either good insurance, or a serious emergency fund, or a combination of both.
5. Yearly Cost Category 4: Grooming and Coat Care
Grooming costs vary wildly between dogs – from almost nothing for some short-haired breeds to a major yearly expense for high-maintenance coats.
5.1 Low-grooming dogs
Short-haired or smooth-coated dogs may only need regular brushing, baths at home and nail trims.
Yearly professional grooming costs can be very low if you learn basic home care.
5.2 High-grooming dogs
Curly, wavy or long-haired dogs often need professional haircuts every few weeks or months.
Matting and neglected coats can lead to painful skin problems – and more expensive grooming sessions.
Regular grooming should be seen as a health cost, not just a beauty expense, for these breeds.
When you choose a breed or mix, always factor in grooming as part of the yearly cost – not just the first haircut as a fun treat.
6. Yearly Cost Category 5: Training, Walking and Daycare
Dogs are social, active animals. Many of the costs here are really about time. If you have less time, you may need to pay other people to help.
6.1 Training classes and behavior support
Puppy classes (usually in the first year) teach basics and social skills.
Follow-up classes or private sessions may be needed for leash walking, recall, fear or reactivity.
Good training reduces damage, accidents and conflict – saving money in the long run.
6.2 Dog walkers and daycare
If you work long hours away from home, paying a dog walker or doggy daycare may be necessary.
These services can become a significant part of your yearly budget, especially in big cities.
6.3 Pet sitting and boarding
When you travel, someone needs to care for your dog – a kennel, pet hotel, in-home sitter or friend.
Boarding costs multiply with the number of trips you take per year and the length of each stay.
Some owners spend very little in this category because they work from home and travel rarely. Others find that walking and boarding become one of their biggest yearly dog expenses.
7. Yearly Cost Category 6: Gear, Toys and Home Wear-and-Tear
Gear and toys don’t seem like much at first, but over years they add up.
7.1 Regular gear replacements
Leads, collars and harnesses wear out or need upgrading.
Dog beds compress or get damaged and need replacement.
Bowls, crates, car seat belts and travel crates may need to be replaced or upgraded over time.
7.2 Toys and enrichment
Chew toys, puzzle feeders, balls and tug toys keep your dog mentally and physically stimulated.
Heavy chewers can destroy toys quickly, increasing yearly toy costs.
7.3 Home and garden damage
Puppies and some adult dogs may damage shoes, furniture, doors, carpets or garden plants.
Good training and management reduce this, but it’s realistic to expect at least some wear-and-tear costs over the years.
8. Small, Medium and Large Dogs: How Yearly Costs Compare
Every dog is unique, but we can still describe general patterns:
8.1 Small dogs
Lowest food and medication costs
Cheaper boarding and walking (where prices depend on size)
Lower insurance premiums in many cases
May need grooming depending on coat type
8.2 Medium dogs
Moderate food and medication costs
Training, walking and boarding similar to small dogs in structure, but sometimes slightly more expensive
Insurance premiums higher than small dogs but lower than giants in many cases
8.3 Large and giant dogs
High food and treat costs
Higher doses for almost all medications, anesthesia and parasite preventives
More expensive surgeries and diagnostics
Higher insurance premiums
Some giant breeds have shorter lifespans but more health costs per year
For many families, the total yearly cost of a large dog can be double or more that of a small dog, even with the same “lifestyle level”.
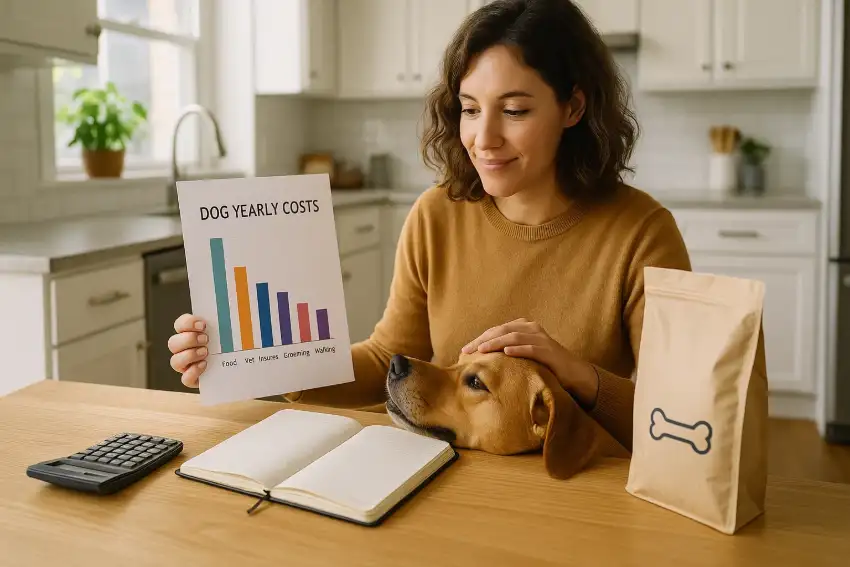
9. Building Your Own Yearly Dog Budget (Step by Step)
Instead of looking for one global number online, build a budget tailored to your dog and your life.
9.1 Step 1: Estimate monthly essentials
Food (based on your dog’s size and chosen brand)
Treats (be realistic about how many you use)
Parasite prevention averaged per month
Insurance premium (if you use it)
Any regular services (dog walker, daycare)
9.2 Step 2: Turn yearly costs into monthly amounts
For each of these, estimate a yearly total and then divide by 12:
Vaccines and wellness exams
Dental cleanings (if recommended every 1–2 years)
Grooming (for professional haircuts or deshedding)
Training classes
Average yearly boarding or pet sitting
Average yearly gear and toys
9.3 Step 3: Add emergency protection
Set a monthly amount to save into a dog emergency fund, or
Factor in expected deductibles and co-pays if you rely on pet insurance
9.4 Step 4: Check if the total feels sustainable
Add everything to see your yearly and monthly totals. Then ask:
Can I cover this comfortably without constant stress?
If prices rise, do I have some flexibility?
Would changing size, breed, food brand or services make the budget healthier?
10. Final Thoughts: A Dog’s Real Cost – and Real Value
Over a decade or more, a dog is likely to cost many thousands of dollars or euros. Food, vet care, insurance, grooming, training, boarding and emergencies all add up.
That might sound intimidating – but it’s also honest. A realistic yearly budget doesn’t kill the dream of having a dog; it protects it. When you know what you’re committing to:
You avoid painful surprises.
You’re less likely to face “money vs dog” crises in emergencies.
You can say “yes” to needed care without destroying your own stability.
The “right” dog for you is not just the cutest one you see online – it’s the dog whose financial needs match your real life. Choose wisely, plan ahead, and your yearly dog budget becomes simply part of life, in exchange for years of companionship, routine, laughter and loyalty that many owners feel are worth far more than the money they spend.