Before you bring home a dog or cat in the US or Europe, it’s easy to focus on the fun parts: choosing a name, buying a bed, imagining walks or cuddle time on the sofa. But responsible pet ownership starts with a less exciting question:
“Can I realistically afford this pet for its entire life?”
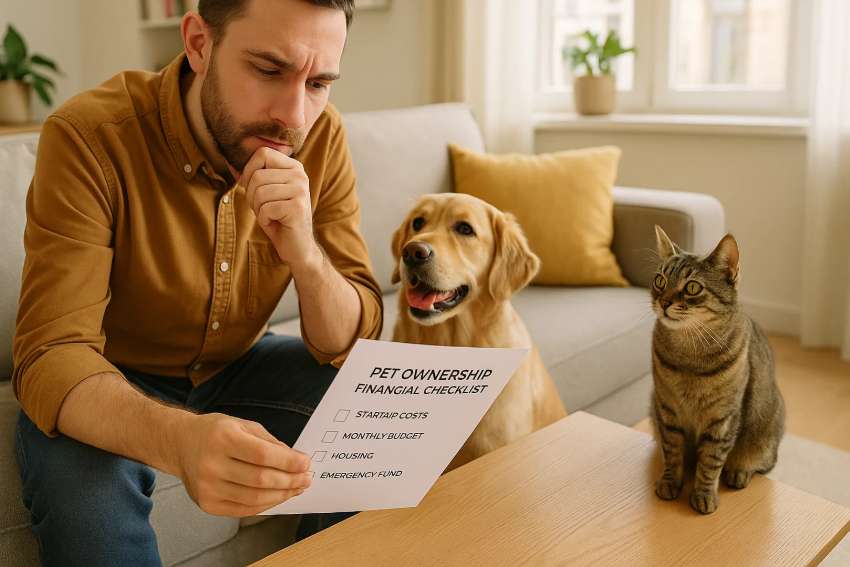
This doesn’t mean you need to be wealthy. It means you need a clear plan. In this guide, you’ll walk through a simple financial checklist to figure out whether you’re ready for a dog or cat right now – or whether you should wait and prepare a bit more first.
1. Understand the Full Timeframe: 10–15+ Years
A pet is not a one-year project. Many:
Cats live 12–18 years (sometimes longer).
Small dogs often live 12–16 years.
Medium and large dogs may live 8–14 years, depending on breed and health.
Your money situation will change over that time – jobs, housing, relationships, kids, moving countries – but your pet’s needs won’t pause for any of it. So your first checklist question is:
“Can I commit to regular spending on this animal for a decade or more?”
2. One-Time Startup Costs: Can You Cover the First 3 Months?
The first few weeks with a new pet are usually the most expensive. Before you adopt or buy, list and price these items in your country:
2.1 Acquisition costs
Adoption fee (usually includes some vet work) or
Breeder price (often much higher, sometimes with less included vet care)
2.2 Initial vet work
First health check at your own vet
Remaining vaccines or boosters
Spay/neuter surgery (if not already done)
Microchipping and registration (where required)
Initial flea, tick and worm treatments
2.3 Basic supplies
Food and water bowls
Bed or blankets
Collar, harness and leash (for dogs)
Litter box, scoop and litter (for cats)
Crate, carrier or pen
Brush, nail clippers and basic grooming tools
Scratching post (cats) or chew toys (dogs)
Checklist question: Do you have enough cash to cover all of this without touching rent money, groceries or emergency savings for yourself?
3. Monthly Budget: Is There Stable Space for a Pet Line?
Next, look at your monthly budget as it is today – not how you hope it will be in the future.
3.1 List your essentials
Rent or mortgage
Utilities (electricity, heating, internet, etc.)
Groceries and basic personal care
Transport
Debt payments (loans, credit cards, etc.)
3.2 Add a realistic pet line
For a dog or cat, include:
Food (based on size and brand)
Litter (for cats)
Routine parasite prevention (spread yearly cost across 12 months)
Pet insurance premium (if you plan to use insurance)
Small contribution to a pet emergency fund each month
Checklist question: After you add this pet line, can you still:
Pay all your essentials comfortably?
Save at least a little each month for your own emergencies?
If the answer is “no”, it might not be the right moment to get a pet yet – even if your heart says yes.
4. Housing Reality Check: Are Pets Allowed and Affordable?
Your home situation can quietly add a lot to the cost of pet ownership, especially in cities.
4.1 Pet-friendly rules
Does your rental contract allow pets (and which types or sizes)?
Are there breed or weight restrictions for dogs?
Do you need written permission from your landlord or building management?
4.2 Pet-related housing costs
Extra security deposit for pets
Monthly “pet rent” charged by some landlords
Potential cleaning fees when you move out
Checklist question: If you had to move in the next 3–5 years, could you realistically:
Find another pet-friendly home in your price range?
Pay pet deposits or higher rent if needed?
If not, it may be safer to wait until your housing is more stable or flexible.
5. Work and Lifestyle: Will You Need Paid Help?
Your schedule affects your pet budget more than you might expect.
5.1 Dogs: time vs money
Dogs need regular walks, company and mental stimulation.
If you work long hours away from home, you may need:
Dog walkers
Doggy daycare
More frequent boarding when you travel
5.2 Cats: attention, but less paid support
Cats usually don’t need walkers or daycare.
They still need daily interaction, play and clean litter boxes.
For trips, you may need a sitter or cattery, but usually less often than dog owners.
Checklist questions:
Given my current job and commute, will I realistically need to pay for walkers, daycare or sitters?
Have I added those costs to my monthly or yearly pet budget?
6. Emergency Plan: What If Something Serious Happens?
At some point, almost every pet will face a serious illness or accident. That doesn’t mean you need thousands saved before you adopt, but you do need a plan.
6.1 Choose your main protection
Pet insurance: accident-only or accident-and-illness, with a premium you can afford long-term.
Emergency fund: money you slowly save in a separate account, for urgent vet care.
Combination: insurance for big events + savings for deductibles and exclusions.
6.2 Honest self-check
If your pet needed an emergency visit next month, where would the money come from?
Could you pay at least part of a big bill without skipping rent or food?
Checklist question: Am I prepared to:
Commit to insurance premiums, or
Commit to building a small emergency fund every month, or
Realistically use a mix of both?
7. Breed and Size Choice: Matching the Pet to Your Wallet
Not all dogs and cats cost the same. Choosing the right type of pet is one of the biggest financial decisions you can make.
7.1 Dogs: size and breed matter
Small mixed-breed dogs: generally cheaper for food, medication and boarding.
Large and giant breeds: higher food bills, medication doses and surgery costs.
High-risk breeds: some purebreds are prone to breathing issues, joint problems or heart disease, meaning higher vet costs.
7.2 Cats: lifestyle and coat type
Indoor-only cats often cost more in litter but less in trauma and infection treatment.
Long-haired cats may need more grooming.
Some pedigree cats have higher risk of genetic diseases.
Checklist question: Am I choosing a species, size and breed (or mix) that fits my real budget – not just my dream Instagram feed?
8. Debt and Savings: Is This the Right Time?
You don’t need to be perfectly debt-free to have a pet. But it does matter what kind of debt you have and how fragile your finances are.
8.1 Risky situations where waiting is wise
You regularly struggle to pay rent or basic bills.
You have high-interest debt (credit cards, payday loans) and can barely keep up.
You have no emergency savings at all for yourself.
8.2 Safer situations
You can pay all essentials comfortably.
Your debt payments are manageable and stable.
You can save at least a small amount each month, even after adding pet costs.
Checklist question: If your financial life is already a constant emergency, is it fair to add a living being who will depend on you for 10–15 years?
9. Emotional Readiness: Money + Mindset
Financial readiness isn’t only about numbers. It’s also about your attitude toward pet spending.
9.1 Being realistic about sacrifices
Are you prepared to spend less on travel, luxury purchases or nights out to pay for pet care when needed?
Can you accept that a portion of your future raises or bonuses may go to vet bills, pet sitting or special diets?
9.2 Handling tough decisions
Are you willing to have hard but honest conversations with your vet about what you can and can’t afford?
Can you separate “I don’t care” (which is not okay) from “I care, but my budget has limits” (which is honest and human)?
Checklist question: Am I ready, emotionally and financially, to treat this pet as a long-term responsibility, not a short-term impulse?
10. Final Verdict: Ready Now, Prepare More, or Wait?
After going through this checklist, you’ll probably fall into one of three categories:
10.1 “Ready now”
You can cover startup costs without crisis.
Your monthly budget has stable space for pet expenses.
Your housing, work schedule and emergency plan are realistic.
You’ve thought carefully about species, size and breed.
→ You may be ready to adopt – especially if you choose a pet whose needs truly match your lifestyle and finances.
10.2 “Almost ready, but need a few months”
You could handle monthly costs, but startup or emergency savings are thin.
Your housing is okay but you need written permission or to adjust your budget.
→ Use the next 3–6 months to:
Save for startup costs.
Build a basic pet emergency fund.
Pay down a bit of high-interest debt.
10.3 “Not yet – and that’s okay”
You struggle with current bills or have unstable housing or income.
Adding a pet would push your finances from fragile to unsafe.
→ This doesn’t mean “never”. It means:
Focus on stabilizing your life first.
Enjoy animals by volunteering at shelters, fostering (where costs are covered) or helping friends with their pets.
Saying “not yet” can be one of the kindest decisions you ever make – for yourself and for the future pet who will eventually join your life when you’re truly ready.
In the end, the financial checklist is not about scaring you away from pet ownership. It’s about making sure that when you say “yes” to a dog or cat, you’re saying “yes” to all the years that come with them – the fun, the routine, the emergencies and the quiet, everyday costs – with your eyes open and your heart prepared.