Pet insurance can feel like a simple question—“Should I get it or not?”—until you see your first emergency vet bill, a chronic allergy diagnosis, or a surprise knee injury. Then the real question becomes: Which type of plan actually fits my pet and my budget? The two most common options are accident-only plans and comprehensive plans (often called accident & illness). They cover very different things, and choosing the wrong type can leave you paying out of pocket when you expected help.
This guide explains how accident-only and comprehensive plans work, what they typically cover (and don’t), how costs and deductibles usually differ, and a practical way to choose the right plan for your dog or cat in the US or Europe.
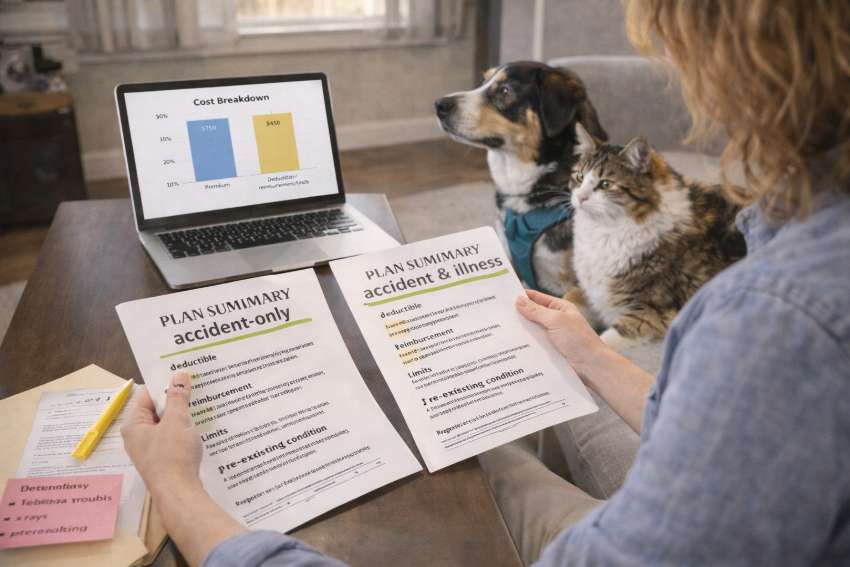
1. Quick Definitions: Accident-Only vs Comprehensive
1.1 Accident-Only Plans
Accident-only insurance is designed to reimburse you for unexpected injuries and emergencies—think “my pet got hurt.”
Typical focus: broken bones, lacerations, swallowed objects, bite wounds, emergency surgery after an accident
Usually does NOT cover: illnesses (ear infections, vomiting from parasites, allergies, cancer), chronic conditions, most diagnostics related to illness
1.2 Comprehensive Plans (Accident & Illness)
Comprehensive plans cover accidents and most illnesses—think “my pet got sick or hurt.”
Typical focus: injuries plus infections, GI issues, skin problems, cancer, chronic disease management, and many diagnostics
Usually does NOT cover: pre-existing conditions, routine wellness care (unless you add a wellness rider), and elective procedures
2. What Each Plan Type Typically Covers (Real-Life Examples)
2.1 Accident-Only: Common Covered Scenarios
Dog tears a nail badly and needs sedation and bandaging
Cat falls from a balcony and needs X-rays and pain meds
Dog swallows a toy and needs emergency imaging and removal
Dog is hit by a car and needs surgery and hospitalization
What often surprises owners: If symptoms are not clearly tied to an “accident,” accident-only may not help—even if the bill is large.
2.2 Comprehensive: Common Covered Scenarios
Recurring ear infections and allergy medications
Vomiting/diarrhea workups, blood tests, imaging
Urinary crystals, blockages, or chronic urinary management
Diabetes, thyroid disease, kidney disease (ongoing care)
Cancer diagnosis and treatment options
What often surprises owners: A single “illness” visit can turn into multiple tests and follow-ups. Comprehensive plans are designed for exactly that kind of slow-burn expense.
3. Cost Differences: Premiums, Deductibles, and Payouts
In most markets, accident-only plans are cheaper each month because they cover fewer scenarios. Comprehensive plans cost more because they’re likely to pay out more often.
3.1 Premiums (Monthly or Annual Cost)
Accident-only: lower premiums, less frequent claims
Comprehensive: higher premiums, more frequent claims potential
3.2 Deductibles
Deductibles can be structured differently depending on provider and region.
Annual deductible: you pay the deductible once per year before reimbursement starts
Per-condition deductible: you pay a deductible for each new condition (can add up for chronic issues)
Why this matters: If your pet develops a chronic issue (allergies, urinary problems), a per-condition model can feel very different than an annual deductible.
3.3 Reimbursement Percent and Limits
Reimbursement: often a percentage of eligible costs after deductible (commonly 70–90% depending on plan)
Limits: may be annual limits, lifetime limits, or condition-based limits depending on the plan
Busy-owner reminder: Always read whether exam fees, diagnostics, and prescription medications are included, because those can make up a big portion of real bills.
4. Waiting Periods and Pre-Existing Conditions (Where People Get Burned)
Most plans have waiting periods before coverage begins, and nearly all exclude pre-existing conditions.
Waiting period: a set time after you enroll before claims are eligible
Pre-existing condition: signs, symptoms, or diagnoses that existed before coverage started (even if not formally diagnosed yet)
Practical rule: The best time to buy pet insurance is when your pet is young and healthy—before the medical record contains chronic clues like “recurrent ear infections,” “intermittent limping,” or “vomiting episodes.”
5. Which Plan Type Fits You? A Simple Decision Guide
5.1 Accident-Only Might Be a Good Fit If:
You primarily want protection from big emergency injuries
Your budget is tight and you need the lowest premium option
You can self-fund most illness care (savings) but want a safety net for accidents
Your pet is older and comprehensive premiums are high (and you want some coverage rather than none)
5.2 Comprehensive Might Be a Better Fit If:
You want help with both emergencies and “normal” illnesses
You worry more about chronic conditions than one-time accidents
You want predictable budgeting for diagnostic workups
You have a breed or species prone to costly health issues
5.3 If You’re Not Sure: Ask Yourself This One Question
“If my pet develops a long-term condition this year, can I comfortably pay for ongoing vet visits and medication?”
If the honest answer is “no,” comprehensive coverage is usually the safer match.
6. Common Scenarios: Which Plan Usually Makes More Sense?
6.1 Young Puppy or Kitten
Often best: comprehensive (lots of unpredictable illness and injury risks early)
Bonus: fewer pre-existing issues in the record
6.2 Healthy Adult Pet (No History)
Depends on your savings: comprehensive for broad protection, accident-only for emergency-only backup
6.3 Older Pet
Often practical choice: accident-only if comprehensive premiums are high and exclusions are many
But: if your older pet is still insurable and you want illness help, comprehensive can still be valuable
6.4 Breeds Prone to Chronic Conditions
Often best: comprehensive (because illness and long-term care are more likely)
6.5 Indoor Cat with Urinary History
Often best: comprehensive (urinary issues can recur and become expensive)
7. How to Compare Plans Quickly (Without Getting Lost)
Use a simple checklist. Compare plans on:
Coverage type: accident-only vs accident & illness
Deductible structure: annual vs per-condition
Reimbursement percentage
Annual or lifetime payout limits
What’s excluded: pre-existing conditions, dental disease, hereditary conditions, behavior therapy, prescription diet food
Exam fees and diagnostics: included or excluded
Claims process: how you submit, how fast reimbursement typically happens, whether direct pay exists in your region
Tip: Pick a plan you can keep long-term. Switching later can turn new issues into “pre-existing,” which defeats the purpose.
8. When to Talk to a Vet or Insurance Specialist
Your veterinarian can’t pick a plan for you, but they can help you plan realistically if you ask the right questions:
“Are there health issues this breed commonly develops?”
“Based on my pet’s record, what might be considered pre-existing?”
“If this symptom becomes recurring, how expensive can it get?”
If you’re getting quotes, ask the insurer to clarify any unclear exclusions in writing so you’re not relying on assumptions.
Final Thoughts: Accident-Only Buys You Injury Protection; Comprehensive Buys You Peace of Mind
Accident-only plans are a budget-friendly safety net for injuries and emergencies, but they won’t help when your pet gets sick—which is often where real costs build over time. Comprehensive plans cost more each month, but they’re designed to cover both sudden accidents and the long list of illnesses and chronic conditions that many pets experience during their lives.
Your action step: decide what you want insurance to protect you from. If you want help with both emergencies and ongoing illness costs, choose comprehensive. If you mainly want a cheaper “oh no” backup for injuries while you self-fund illness care, accident-only can be a reasonable option.